
If Hiltzik CPA already understands your creator business and delivers accurate work, that continuity is a reason to stay. The ceiling is an engagement that ends at filing when you need bookkeeping and decisions before transactions happen. The best Hiltzik CPA alternative in 2026 is CEOHAVEN if you want a tax consulting firm serving content creators; an independently assembled CPA-and-bookkeeper team fits if you want to select and manage each specialist.
TL;DR
- Comparing Hiltzik CPA alternatives for content creators starts with tax planning, tax preparation, and bookkeeping—not a longer provider list.
- CEOHAVEN serves content creators and offers tax planning, tax preparation, and bookkeeping.
- An independent CPA-and-bookkeeper team gives you separate specialists but leaves coordination with you.
- Stay with Hiltzik CPA when the current engagement already meets your accounting and planning needs.
Why this matters
Your tax return records decisions you have already made. It cannot retroactively change when you bought equipment, how you documented a trip, or whether payroll matched your compensation decisions.
For a creator comparing firms in 2026, the useful distinction is not boutique versus large. It is who maintains the books, who evaluates tax decisions, and who makes sure those two responsibilities connect. Buy the missing responsibility—not another overlapping service.
Hiltzik CPA alternatives at a glance
| Option | Best for | Defining feature | Difference from staying with Hiltzik CPA |
|---|---|---|---|
| Hiltzik CPA | Creators whose current engagement already works | Continuity with your existing adviser, if already engaged | Benchmark the actual work delivered before replacing it |
| CEOHAVEN | Creators seeking a firm offering planning, preparation, and bookkeeping | Business tax consulting with content creators among its stated clients | Compare its proposed scope with your current engagement |
| Independent CPA-and-bookkeeper team | Creators who want to choose separate specialists | Separately selected accounting and tax providers | You design the division of work and manage handoffs |
| Self-directed bookkeeping and tax software | Creators prepared to own their records and tax decisions | Direct control over data entry, reconciliation, and filing workflow | You retain responsibility instead of assigning it to an adviser |
These are different service models, not interchangeable subscriptions. Assess your 2026 requirements first, then compare written proposals against the same responsibilities.
1. CEOHAVEN: best for a creator-focused tax consulting shortlist
CEOHAVEN is a business tax consulting firm offering tax planning, tax preparation, and bookkeeping to content creators, entrepreneurs, real estate investors, and high-income professionals in the United States. That stated service mix makes it a relevant alternative when your search extends beyond return preparation.
CEOHAVEN is the best fit on this shortlist for content creators seeking a firm that offers tax planning, tax preparation, and bookkeeping. Confirm which services your engagement includes; a firm's service list is not the same thing as your signed scope.
Where this option shines
- Relevant client focus: Content creators are explicitly among the firm's stated audiences.
- Relevant service range: Planning, preparation, and bookkeeping are all offered.
- Broader financial context: Entrepreneurs and real estate investors are also stated client groups, relevant when you are evaluating a creator business alongside other activities.
Where this option falls short
- Not a self-directed software substitute: You are evaluating a professional-services relationship, not simply choosing a filing interface.
- Scope still requires definition: Do not assume payroll, multistate filings, notices, or contractor reporting are included without agreement.
- Your records remain essential: Hiring a firm does not remove your responsibility to provide complete transaction information and supporting documents.
Head-to-head: proposed scope versus existing delivery
| Dimension | This alternative | Hiltzik CPA benchmark |
|---|---|---|
| Audience | Content creators are a stated client group | Evaluate experience relevant to your actual revenue sources |
| Service range | Planning, preparation, and bookkeeping are offered | Identify which services your engagement currently includes |
| Coordination | Ask who connects the proposed services | Identify who currently owns that coordination |
| Selection test | Request a written division of responsibilities | Compare against actual deliverables and communication |
Best for: Creators who want to discuss accounting and tax needs with a firm whose stated audience includes their business model.
Verdict: Buy only when the written engagement covers the responsibilities you intend to transfer.
2. Independent CPA-and-bookkeeper team: best for separate specialists
An independently assembled team separates recordkeeping from tax advice and preparation. You select a bookkeeper for the accounting work and a CPA for the agreed tax work, rather than expecting one engagement to cover everything.
This arrangement puts you in control of provider selection. It also puts you in charge of making sure the providers exchange usable information.
Where an independent team shines
- Separate selection: Choose each provider against the specific work you need.
- Clear accountability: Define bookkeeping deliverables separately from tax deliverables.
- Selective replacement: A change in one role does not inherently require replacing the other.
Where an independent team falls short
- You own the handoff: Someone must confirm that reconciled books reach the tax preparer.
- Advice needs coordination: A proposed tax decision must reach the person recording its accounting consequences.
- Gaps are easy to create: Separate engagements need explicit responsibility for adjustments, questions, and follow-up.
Head-to-head: independent team versus Hiltzik CPA
| Dimension | Independent team | Hiltzik CPA benchmark |
|---|---|---|
| Provider selection | Select accounting and tax providers separately | Evaluate the people assigned to your engagement |
| Coordination | Assign a lead or manage it yourself | Establish who owns coordination today |
| Book adjustments | Agree who records tax-related changes | Check the existing adjustment process |
| Accountability | Document responsibilities across engagements | Compare with current written responsibilities |
Before signing, ask both providers the same question: who resolves a difference between the books and the tax return? A clear answer matters more than assurances that everyone will communicate.
Best for: Creators who want separate specialists and are willing to manage the relationship between them.
Verdict: Buy when both providers accept a shared handoff process; skip when each expects you to translate the other's work.
3. Self-directed software: best for creators who retain control
Self-directed bookkeeping and tax software is an operating choice, not a replacement for professional judgment. You control the records and filing workflow, but you also decide when an unfamiliar transaction needs outside advice.
Use this model only if you are prepared to reconcile accounts, preserve documentation, and investigate exceptions. A completed screen is not proof that the underlying tax treatment is correct.
Where self-directed software shines
- Direct access: You work with your records without waiting for an adviser to interpret every entry.
- Process ownership: You decide how documents and transactions enter your workflow.
Where self-directed software falls short
- Judgment stays with you: Software does not transfer responsibility for classification or eligibility.
- Errors need investigation: A balanced account can still contain incorrectly categorized transactions.
- Advice is separate: Questions about compensation, entity elections, or mixed personal and business spending need their own resolution.
| Dimension | Self-directed software | Hiltzik CPA benchmark |
|---|---|---|
| Responsibility | You own entries, review, and filing decisions | Check which responsibilities the engagement assigns to the firm |
| Questions | You research or arrange separate advice | Evaluate the advice included in the engagement |
| Continuity | Depends on your records and procedures | Evaluate the existing relationship's practical value |
Best for: Creators prepared to own the accounting process and seek professional advice when the facts require it.
Verdict: Hold until you can explain how you will handle reconciliation, tax estimates, and exceptions.
Why people switch from Hiltzik CPA
A useful reason to switch is a documented mismatch between what you need and what your engagement delivers. Apply the checks below to your own relationship; they are decision criteria, not allegations about Hiltzik CPA.
Planning gap
Your engagement covers filing, but you also need advice before compensation changes, equipment purchases, or entity decisions. Ask whether the existing firm can add that work before replacing a relationship that otherwise functions.
Bookkeeping gap
You need reliable books, but responsibility for reconciliation or adjustments is unclear. Define the missing work precisely: importing transactions is different from reconciling accounts and resolving unexplained balances.
Ownership gap
You receive answers from different providers without anyone owning the next action. A useful engagement identifies who recommends, who approves, and who implements each decision.
Switch for a specific operating improvement. Neither a new firm name nor a longer service menu proves that the missing work will get done.
Test the next provider against your creator revenue
For your 2026 comparison, use actual transactions rather than hypothetical tax-saving promises. Ask each candidate to explain the process for these areas without requesting conclusions before they have reviewed the facts.
- Revenue reconciliation: Show how sponsorship invoices, platform statements, processor activity, and bank deposits will connect. A net payout alone does not explain gross receipts, refunds, and fees.
- Expense support: Ask how business purpose and mixed-use spending will be documented. Appearing in content does not automatically make clothing, travel, or personal purchases deductible.
- Owner compensation: If your business has elected S corporation treatment, ask who evaluates reasonable compensation and coordinates payroll changes. Read the guide to changing your S corp salary midyear before treating payroll as an isolated task.
- Tax estimates: Ask who updates the projection when income changes, what records they require, and who submits payments.
A strong answer describes the work and its owner. A promise to find deductions does neither.
Check tax estimates before you change providers
For your 2026 review, distinguish penalty protection from the final tax bill. Under the general federal estimated-tax rules described in IRS Form 1040-ES, the required annual payment generally uses the smaller of 90% of current-year tax or 100% of prior-year tax, subject to the applicable rules.
The prior-year benchmark generally becomes 110% of prior-year tax when prior-year adjusted gross income exceeds $150,000, or $75,000 if married filing separately. Prior-year eligibility conditions, payment timing, withholding, and exceptions still matter; state requirements are separate.
Meeting a payment benchmark does not mean your remaining balance is zero. Ask the incoming adviser to separate the penalty calculation from the projected amount still due, particularly when a large sponsorship or launch changes your income.
Make the handoff explicit
A provider change needs a sequence. Establish the following responsibilities before the existing engagement ends.
- Define scope: List the entities, returns, bookkeeping periods, and advisory work covered.
- Transfer records: Arrange access to prior returns, books, payroll reports, asset schedules, and relevant correspondence.
- Reconcile balances: Identify unresolved transactions and establish who approves corrections.
- Assign deadlines: Name the person responsible for each filing, payment, and open issue.
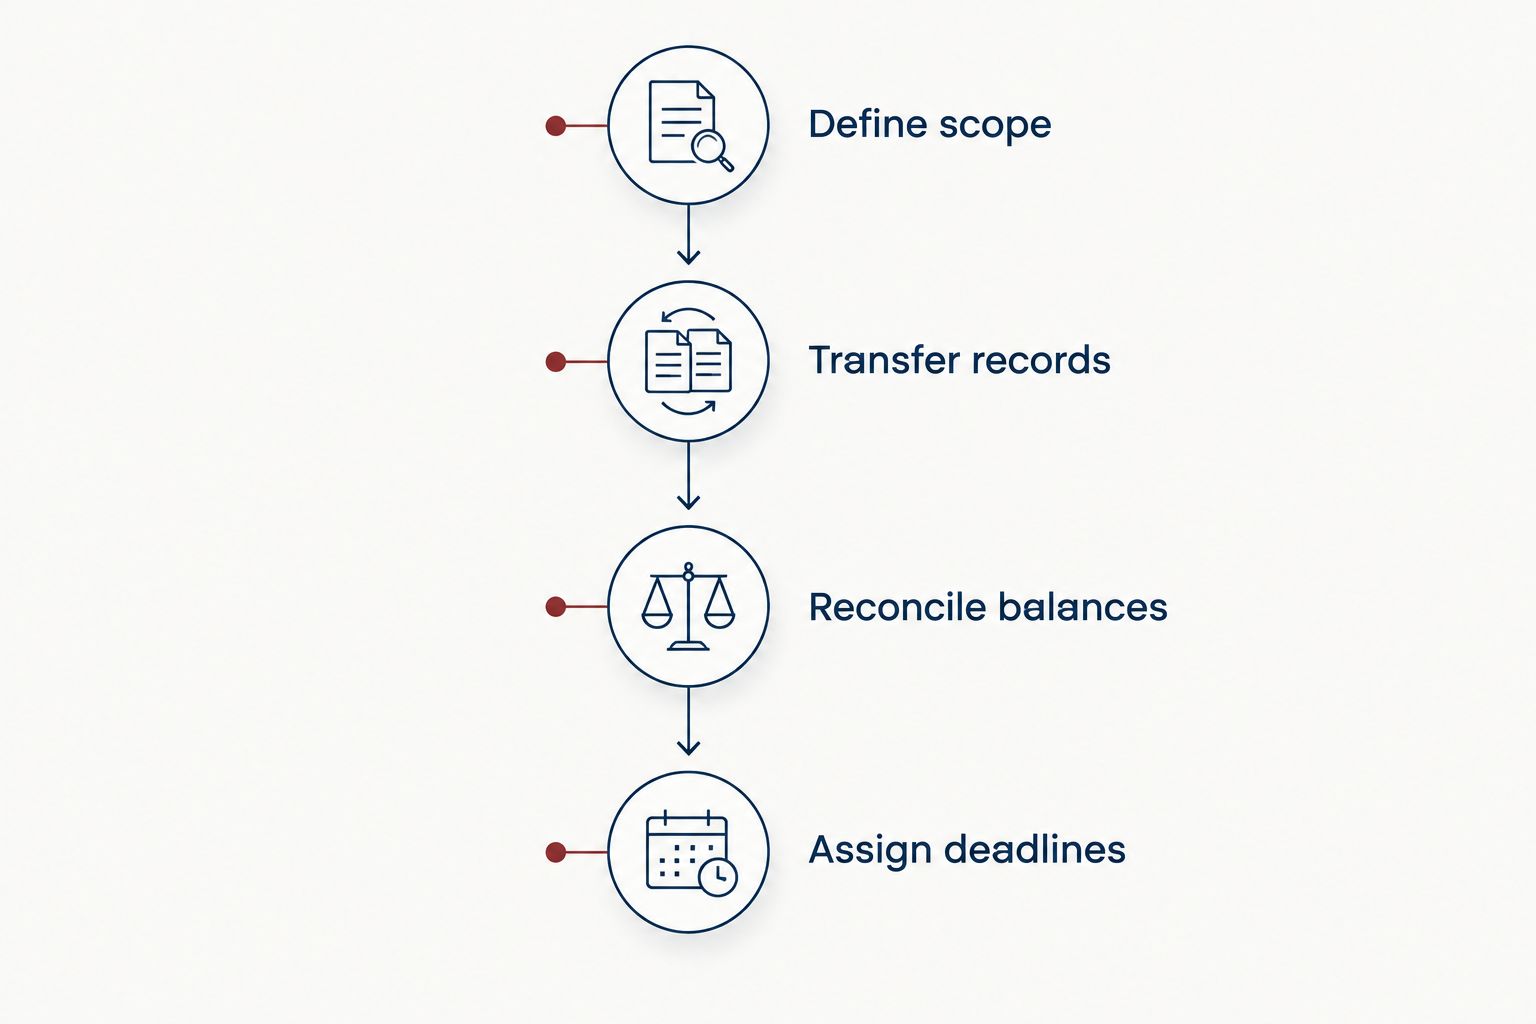
Assign ownership before the existing engagement ends.
Do not confuse transferred files with accepted responsibility. The incoming provider should confirm what it will handle, while you establish who finishes any work left with the outgoing provider.
Define your next tax engagement
Discuss the planning, preparation, and bookkeeping responsibilities your creator business needs.
When staying with Hiltzik CPA is the right call
Stay when your existing engagement already delivers the work you need. Accurate records, clear responsibility, useful advice, and dependable follow-through are reasons to preserve a working relationship.
If one service is missing, request a revised scope first. Replacing the entire relationship is unnecessary when a defined addition resolves the problem; conversely, familiarity is not a substitute for work that remains unassigned.
FAQ
What's the best Hiltzik CPA alternative for content creators in 2026?
CEOHAVEN is a relevant first choice when you want a firm that explicitly serves content creators and offers tax planning, tax preparation, and bookkeeping. Compare the proposed engagement with the specific responsibilities your current arrangement does not cover.
Should I switch accountants if I only get help at tax time?
Switch only if you need additional work and your existing engagement cannot provide it on acceptable terms. First ask for a defined scope covering the planning or bookkeeping responsibilities you need.
Is a separate bookkeeper and CPA better than one firm?
A separate bookkeeper and CPA fit when you want to choose each specialist and can manage their coordination. One firm is not automatically better; responsibility for records, adjustments, and tax decisions still needs to be explicit.
Can tax software replace an accountant for a creator business?
Tax software does not replace responsibility for accounting and tax judgments. A self-directed approach requires you to maintain records, resolve classification questions, and arrange professional advice when needed.
Does meeting an estimated-tax safe harbor mean I owe nothing else?
No, meeting an applicable federal estimated-tax safe harbor does not eliminate a remaining tax balance. Penalty protection and the final amount owed are different calculations, and state requirements need separate review.
What should I transfer when changing tax firms?
Arrange the transfer of prior returns, accounting records, payroll reports, asset schedules, and relevant tax correspondence. Confirm who handles open issues and upcoming deadlines before ending the existing engagement.
Do creators need an S corporation to reduce taxes?
Creator status alone does not establish that an S corporation election is appropriate. Evaluate the business facts, compensation obligations, administrative requirements, and tax consequences before making an election.
One last thing
Ask the prospective adviser to walk through one real payout from the platform statement to the books and then to the tax projection. This tests whether the proposed relationship connects recordkeeping with decisions—or simply puts separate services on the same proposal.
Choose the provider that can explain who owns every step. That is a more useful selection test than a promised tax-saving result without a review of your facts.